How Loan Term Length Quietly Controls How Much Interest You Actually Pay
Stretching a $10,000 loan from 3 to 5 years at 15% APR adds $1,794 in pure interest. Here's why longer terms cost most borrowers far more than they realize.
Stretching a $10,000 loan from 3 to 5 years at 15% APR adds $1,794 in pure interest. Here's why longer terms cost most borrowers far more than they realize.
A $5,000 credit card balance at 20% APR compounded daily can exceed $6,100 in a year—without a single new purchase. Here's exactly how that happens.
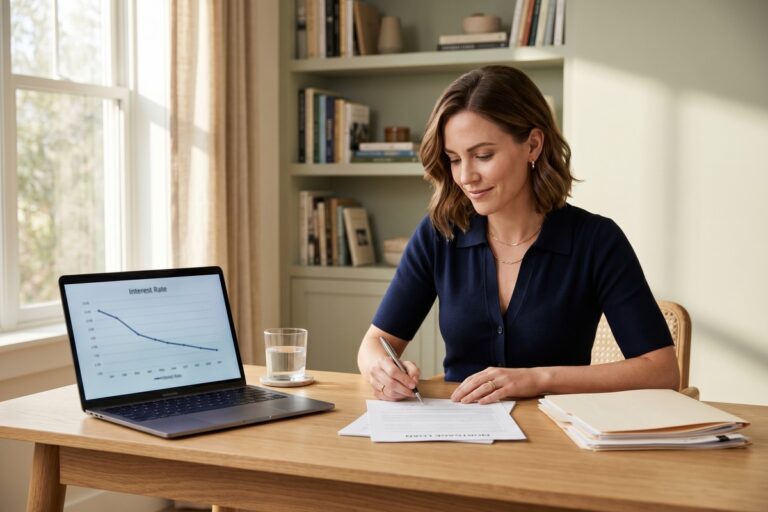
Mortgage rates are stuck in the mid-to-upper 6% range—act within your 30–60 day lock window now or risk paying hundreds more per month if the Fed moves rates higher.
Fixed rates range from 8–36%, while variable rates start lower but risk rising. See which loan type matches your financial priorities.
A DTI above 40% can raise your mortgage or personal loan rate by 1–3 percentage points and push you into subprime terms. Here's exactly how lenders price that risk.
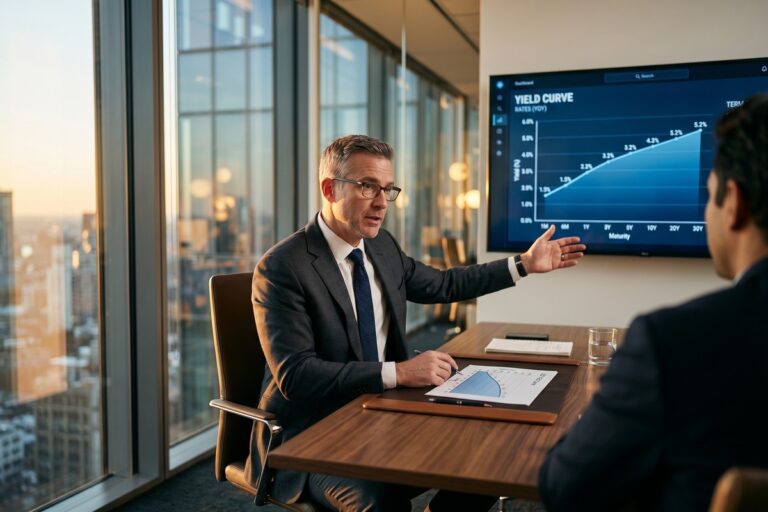
The 10-year Treasury sits near 4.3% and mortgage rates are stuck above 6.5%. Here's what the yield curve's slow re-steepening means for your borrowing costs.
One late payment can drop your credit score by up to 110 points and push your personal loan APR past 25%. Here's exactly how lenders price that risk against you.
Auto loans average 7.1% vs 12.4% for personal loans—a gap that compounds fast over 48–72 months. See when each option actually makes sense for your purchase.
Top online lenders beat traditional banks by 2–5 percentage points for qualified borrowers. Here's how to prequalify, compare APRs, and find your lowest rate.
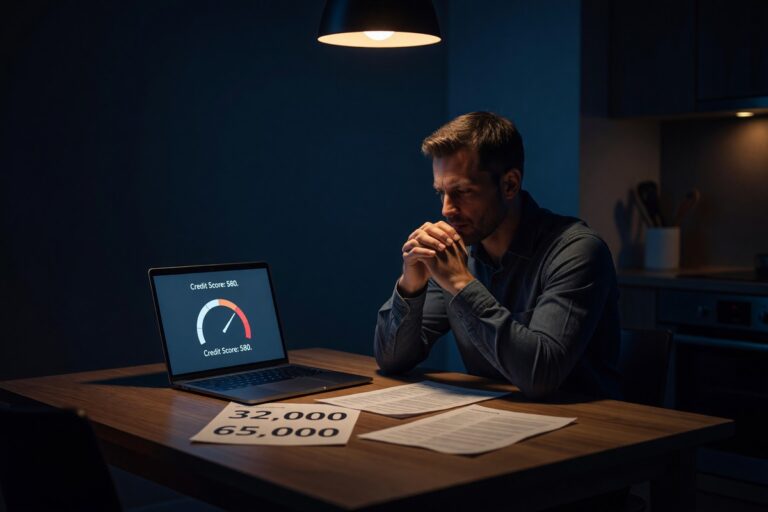
A 580 credit score can cost you $15,000 more in interest on a $25,000 loan than a 760 score does — here's exactly how risk-based pricing works against you.