How Digital Lending Platforms Are Replacing Traditional Bank Loans
Fintech platforms now approve thin-credit borrowers at rates 30% higher than banks—here's how AI underwriting and a $500B market are redrawing the lending landscape.
Fintech platforms now approve thin-credit borrowers at rates 30% higher than banks—here's how AI underwriting and a $500B market are redrawing the lending landscape.
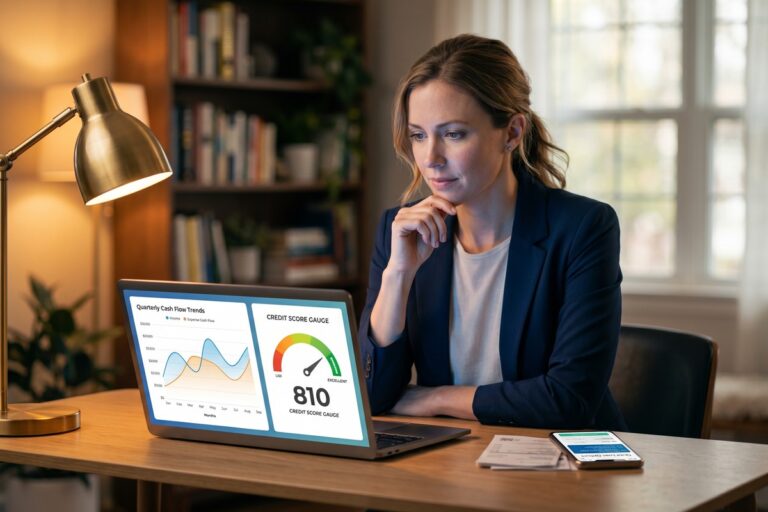
45 million Americans are credit invisible to FICO models. Here's how cash flow lending compares to credit score lending—and which platform approach actually funds more borrowers.
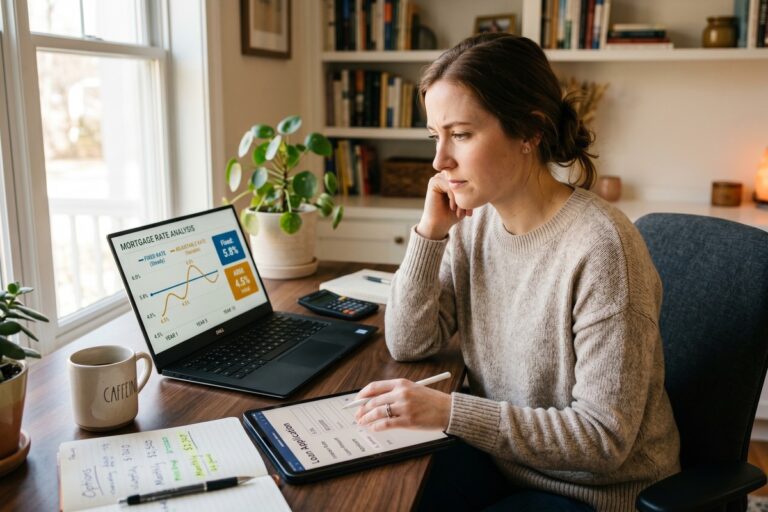
Variable rates start 2–4 points lower than fixed, but borrowers on digital platforms taking loans past 36 months almost always pay more. Here's what the math actually shows.
Origination fees alone can run 1%–8% of your loan amount. Here's how digital lending platforms layer charges that quietly offset your refinancing savings.
Lenders using automated income verification approve borrowers up to 80% faster — here's how bank feeds, payroll APIs, and tax record pulls actually work.
Fintech lenders approve caregivers with irregular income using alternative data and bank patterns. Platforms like Upstart and Dave offer personal loans with APRs far below payday loans.
On a $45,000 salary, most digital lenders approve $5,000–$40,000 in personal loans. Here's how DTI, credit score, and platform rules shape your real ceiling.