How Fintech Lenders Decide Your Loan Limit — And What You Can Do to Raise It
Fintech algorithms cap most first-time borrowers at $10K–$15K, but a DTI below 36% and verified income can push your limit to $50,000 or more. Here's how the math works.
Fintech algorithms cap most first-time borrowers at $10K–$15K, but a DTI below 36% and verified income can push your limit to $50,000 or more. Here's how the math works.
The alternative lending market hit $800B in 2026—and grabbing the first instant-approval app could cost you. Here's how fintech loans and P2P platforms actually compare.
Five buried charges—including prepayment penalties and ACH fees—can push your loan's real APR 3–8 points above the advertised rate. Here's what to look for before you sign.
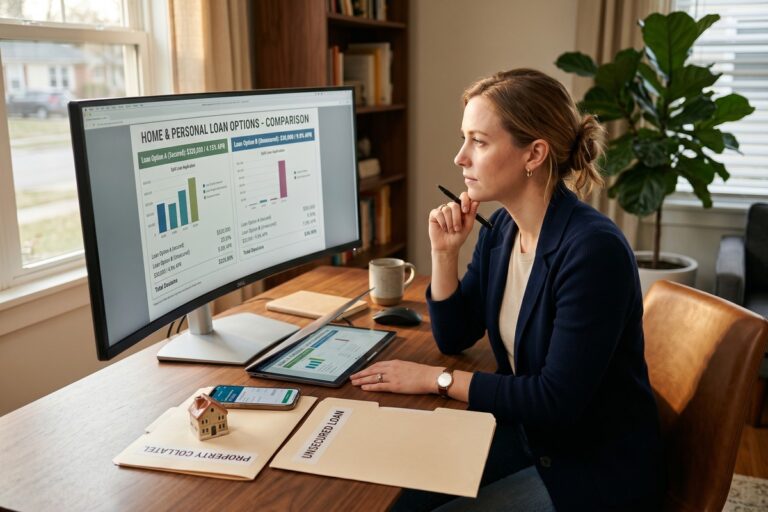
Secured digital loans run 6%–12%; unsecured ones can hit 36%. Here's how your credit score and collateral determine which loan type actually saves you money.
Nearly 21% of credit applicants get denied by banks — platforms like Upstart, LendingClub, and Avant approve borrowers from 580 and decide in under 24 hours.
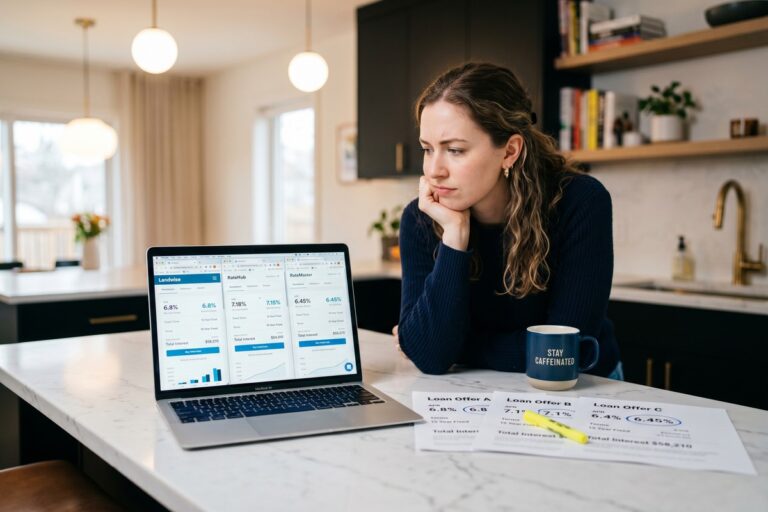
Learn about comparing APR digital lenders. Discover hidden fees, rate structures, and key factors most borrowers overlook when evaluating digital lending platforms.
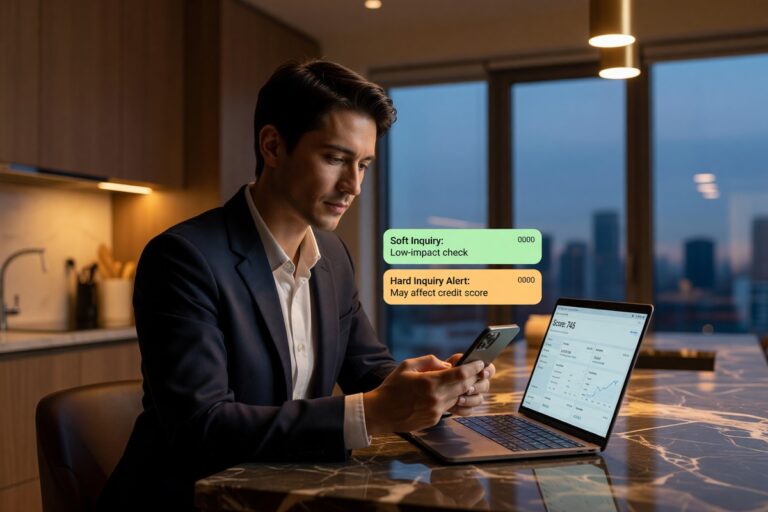
A hard pull can drop your score 5–10 points and sits on your report for 2 years—yet most borrowers trigger one without realizing it by accepting a pre-qualified offer.
Fintech lenders now set your rate in seconds using live data — strong borrowers may see 7.99%, while thin profiles can pay 10–15 points more. Here's how to prepare.
Cash advances cost under $15 for small urgent needs, but installment micro-loans at sub-200% APR work better for $500–$5,000 gaps. Here's how to choose.
45 million Americans have unscorable credit files — but fintech lenders now approve them using bank cash flow, rent history, and income data, often within 24 hours.