Fintech Small Business Loan Pricing in 2026: When the 14–99% APR Makes Sense
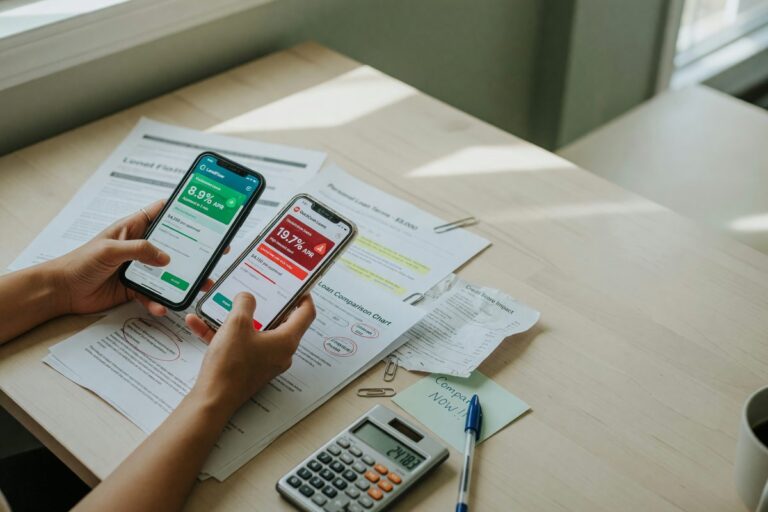
Fintech small business loans carry APRs of 14–99% versus 6.8–11% at banks. See when speed justifies the premium and when traditional lending wins.
Fintech small business loans carry APRs of 14–99% versus 6.8–11% at banks. See when speed justifies the premium and when traditional lending wins.
Mainstream lenders auto-deny recent bankruptcies, but secured products and credit unions with manual review still approve. See which platforms say yes and what rates to expect.
Refinancing cuts your rate only if it drops 1-2%+ and you have 3+ years left. Origination fees up to 8% often erase monthly savings—here's how to do the math.
Lenders keep your financial data for at least 7 years after closing—and often sell it. Here's when to request deletion and how to protect yourself from marketing abuse.
A 620 credit score and applying within 60 days of peak earnings can make or break your approval. Here's how timing—not creditworthiness—determines your odds.
A $7.2 trillion market by 2030—embedded lending is reshaping how people borrow, skipping banks entirely through apps like Shopify and Uber.
Fintech algorithms cap most first-time borrowers at $10K–$15K, but a DTI below 36% and verified income can push your limit to $50,000 or more. Here's how the math works.
Newlyweds borrowing jointly can qualify for up to $100,000 with approval in 24–48 hours. Here's how combined credit profiles and co-borrower apps actually work.
Banks reject multi-property landlords despite positive cash flow. Fintech platforms approve in 24-10 days, use rental income for underwriting, and require no property lien—letting you renovate and raise rents while keeping equity intact.
Fintech installment loans average 11–13% APR vs 21.5% for revolving credit—here's why the loan wins for repairs over $5,000 and the credit line wins under.