How Embedded Lending Is Now Replacing 1099 Income Verification
The $115.8 billion embedded finance market is shifting gig-worker lending away from tax returns to real-time transaction data. Here's what changed for self-employed borrowers.

The $115.8 billion embedded finance market is shifting gig-worker lending away from tax returns to real-time transaction data. Here's what changed for self-employed borrowers.
Gig workers paid an 18.5% effective interest rate on personal loans in 2026, compared to 13.8% for salaried borrowers. Income volatility adds a 5.7 percentage point premium regardless of credit score.
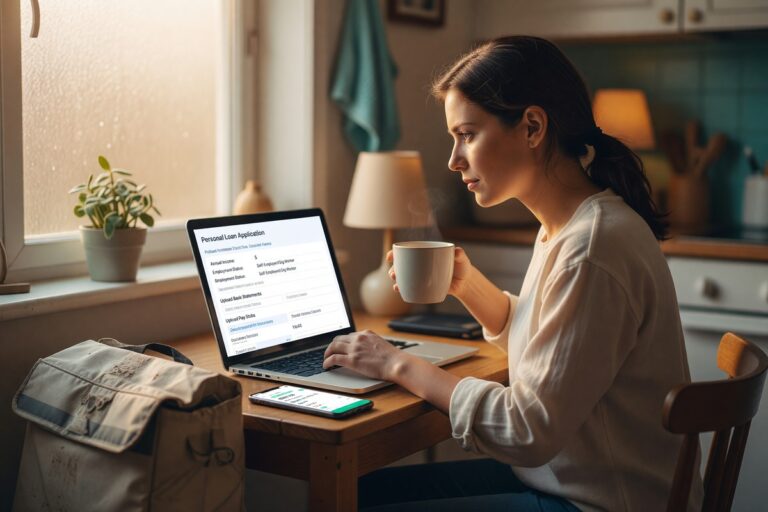
59 million gig workers can't produce W-2s, but bank statement analysis and platforms like Argyle or Pinwheel help them qualify. Here's what lenders actually check.

Irregular earners get flagged in underwriting even when they out-earn W-2 workers. Here's how to document multi-stream income and qualify for 11–24% APR personal loans.
Gig workers pay 125–300 basis points above standard rates because lenders struggle to verify inconsistent income. Here's what changed in early 2025.

Gig workers can now qualify for installment loans with APRs starting at 5%—no credit check required. See which fintech lenders accept bank data and 1099 income instead of pay stubs.