5 Alternatives to Traditional Personal Loans That Offer Lower Interest Rates in 2026
Home equity loans hit 7.43%-8.08% while personal loans average 17.36%. Compare five cheaper borrowing options, including 0% credit cards and HELOCs.

Home equity loans hit 7.43%-8.08% while personal loans average 17.36%. Compare five cheaper borrowing options, including 0% credit cards and HELOCs.
Borrowers with multiple loans above 11-13% APR can save real money by consolidating—but only if the new term doesn't stretch too long. See when the math works in your favor.
Debt consolidation or income investment? See which personal loan strategy wins when inflation climbs—and when a 11.40% rate actually makes sense.
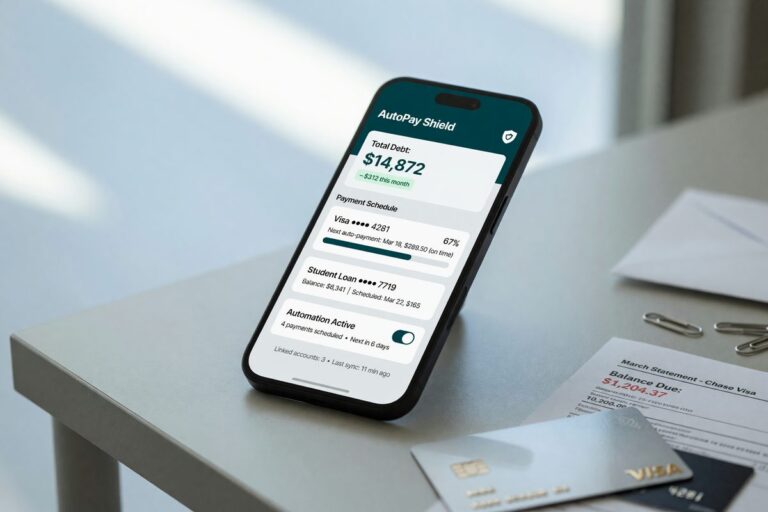
Automated fintech debt repayment pays off if you earn stable income and carry $5,000+ in debt—but app fees can erase savings faster than you think. See when it's worth it.
One single mother replaced 20%-APR credit card balances with a 7.99% fintech loan — here's how platforms like SoFi and Upstart made consolidating $30,000 possible.
Learn about personal loans debt consolidation. Compare the best lenders, rates, and terms to simplify payments and save money on debt in 2026.
47% of users cut unsecured debt by 30% in a year using these apps. See which platforms deliver real payoff time reductions and the gaps to avoid.
A 0% intro APR beats a 12.31% personal loan—but only if you clear the debt in 12–21 months. Here's how to tell which option actually saves you more money.
Consolidating high-interest debt before a mortgage application can lower your rate by improving DTI and credit utilization—even lenders price in 0.25% steps for modest credit improvements.
A digital loan to pay off shared divorce debt alone works if you lock in a rate at least 2 points lower—otherwise you risk carrying double liability.