No Origination Fee Loans Worth It? When the Trade-Off Actually Makes Sense
No origination fee loans make sense if your credit score hits 720 and you lock in under 10.5% APR. Below 680 or planning quick repayment? Skip them.

No origination fee loans make sense if your credit score hits 720 and you lock in under 10.5% APR. Below 680 or planning quick repayment? Skip them.
Newly sober borrowers who complete a credit-builder digital loan see average 48-point score gains in a year—but only if you can commit to reliable monthly payments.
Most digital lender soft pull offers range $25,000–$50,000, but lenders build in a 20–30% safety buffer. See how to maximize your prequalified amount.
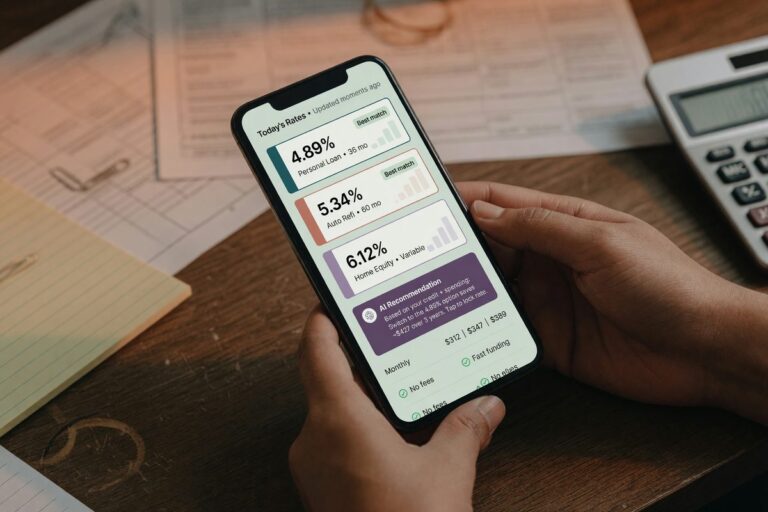
AI loan matching platforms deliver the biggest payoff for borrowers under 680 FICO or those comparing 10+ lenders at once. The real difference: whether you get genuinely different offers or just re-ranked duplicates.
Unplanned equipment downtime costs small businesses $8,000/hr. Fintech lenders now offer $5K–$500K in unsecured capital within 24–48 hours—no collateral required.
Fewer than 30% of approved borrowers actually receive same-day funds. See which platforms like LightStream, Upstart, and SoFi hold up under scrutiny.
Learn about debt to income digital lending. Discover how your DTI ratio affects online loan approvals and what you can do to improve your chances.
Newlyweds borrowing jointly can qualify for up to $100,000 with approval in 24–48 hours. Here's how combined credit profiles and co-borrower apps actually work.
26 million Americans have no scoreable credit history—here's how fintech lenders are using real bank transaction data to approve loans traditional scoring would reject.
Over 60 million Americans now share bank data with lenders via open banking APIs—here's how real transaction history is replacing FICO scores in credit decisions.