Debt-to-Income Ratio on Digital Lending Platforms: The Number That Quietly Kills Your Application
Learn about debt to income digital lending. Discover how your DTI ratio affects online loan approvals and what you can do to improve your chances.

Learn about debt to income digital lending. Discover how your DTI ratio affects online loan approvals and what you can do to improve your chances.
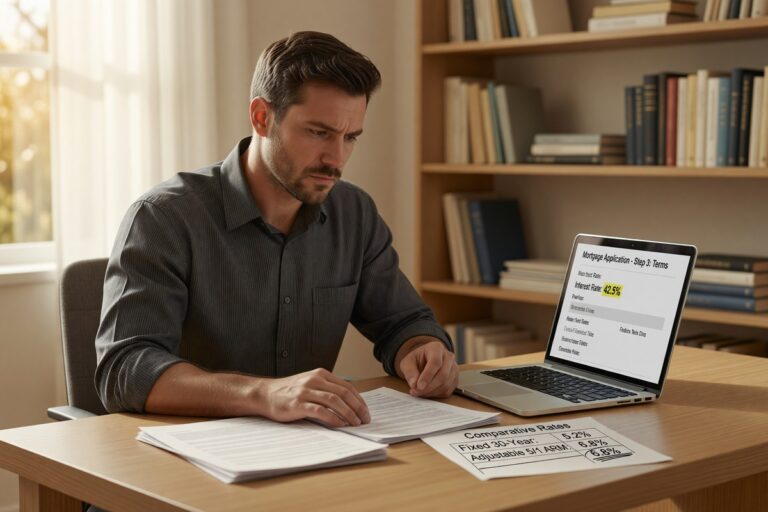
A DTI above 40% can raise your mortgage or personal loan rate by 1–3 percentage points and push you into subprime terms. Here's exactly how lenders price that risk.
Switch to income-driven repayment, boost your credit above 720, and shop multiple lenders. First-time buyers with student loans can qualify for competitive mortgage rates.
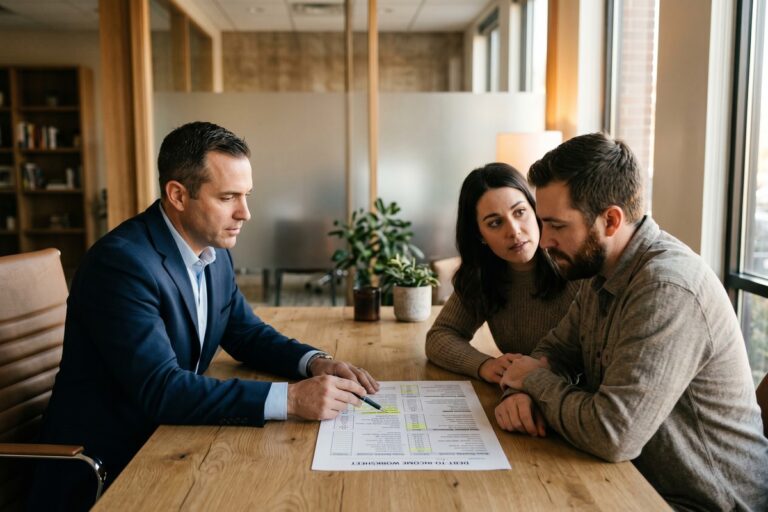
Learn about debt to income ratio lending. Discover why lenders scrutinize your DTI more than you expect and how it shapes your borrowing power.
A DTI above 43% can add 0.5%–1.5% to your mortgage rate — or get you denied outright. Here's why lenders weight cash flow over credit history.
Consolidating high-interest debt before a mortgage application can lower your rate by improving DTI and credit utilization—even lenders price in 0.25% steps for modest credit improvements.