Buy Now Pay Later vs Personal Loans: What Actually Costs You Less
Missed a BNPL payment? Fees hit fast, and deferred-interest plans can charge up to 29.99% APR retroactively. Personal loans average 12.35% APR—often the cheaper call above $500.

Missed a BNPL payment? Fees hit fast, and deferred-interest plans can charge up to 29.99% APR retroactively. Personal loans average 12.35% APR—often the cheaper call above $500.
Federal student loan rates now run 6.53%–9.08%, putting them neck-and-neck with market returns. Here's how to decide whether to pay down debt or invest first.
37% of Americans can't cover a $400 emergency—here's why experts say fund that cushion first, then move it to a 4.5–5.0% APY high-yield account.
Learn about windfall money decisions. Discover smart strategies to pay off debt, grow investments, or build savings when unexpected money comes your way.
With inflation at 2.7% and top savings accounts paying up to 5.00% APY, your real purchasing power hinges on one gap. Here is how to tell which side you are on.
Borrow $2,000–$5,000 at 10–15% APR to jumpstart your emergency fund instead of turning to payday loans or credit cards. See if this strategy fits your situation.
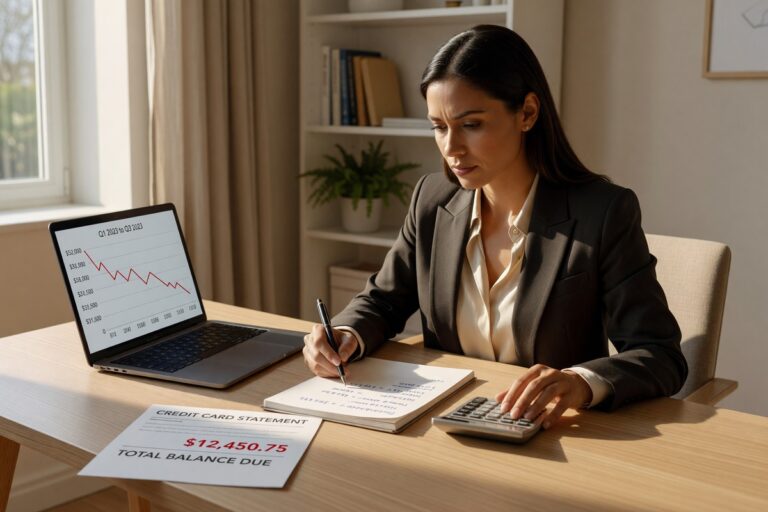
Credit card rates average 21% even as the Fed cuts—meaning debt above 7% beats investing every time. Here's how to run the numbers for your situation.
That $5,000 raise adds roughly $270–$320 a month after federal taxes, not the $416 most people expect. Here's what actually hits your paycheck and how to use it.
37% of Americans can't cover a $400 emergency. Before you invest another dollar, here's how to decide what your money actually needs to do first.
37% of Americans can't cover a $400 emergency without borrowing. Set up 3–5 sinking funds alongside one emergency account and break that cycle in two weeks.