No Origination Fee Loans Worth It? When the Trade-Off Actually Makes Sense
No origination fee loans make sense if your credit score hits 720 and you lock in under 10.5% APR. Below 680 or planning quick repayment? Skip them.

No origination fee loans make sense if your credit score hits 720 and you lock in under 10.5% APR. Below 680 or planning quick repayment? Skip them.
A $28,400 solar loan at 5.99% instead of 11.9% saves $4,100 in interest. See how green personal loans work, who qualifies, and what rates actually look like.
Borrowers with multiple loans above 11-13% APR can save real money by consolidating—but only if the new term doesn't stretch too long. See when the math works in your favor.
Fair-credit borrowers face 20%+ APRs on P2P platforms after fees, while credit unions offer rates 2–3 points lower than both banks and peer lenders.
Fintech small business loans carry APRs of 14–99% versus 6.8–11% at banks. See when speed justifies the premium and when traditional lending wins.

A $1,000 origination fee savings can vanish if the interest rate climbs. See how to compare digital lenders and calculate what you'll actually pay.
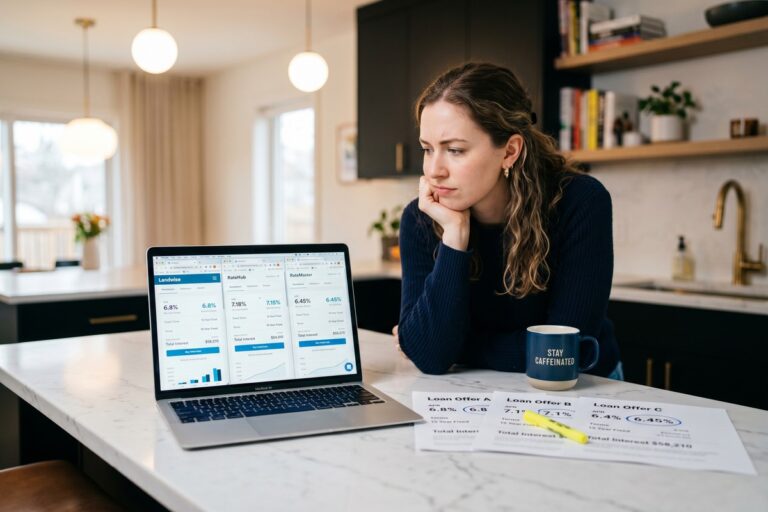
Learn about comparing APR digital lenders. Discover hidden fees, rate structures, and key factors most borrowers overlook when evaluating digital lending platforms.