What Happens to Your Credit Score When You Take Out a Personal Loan
A hard inquiry drops your score 5–10 points at application, but on-time payments can rebuild it—while a missed payment can cost you 100 points or more.

A hard inquiry drops your score 5–10 points at application, but on-time payments can rebuild it—while a missed payment can cost you 100 points or more.
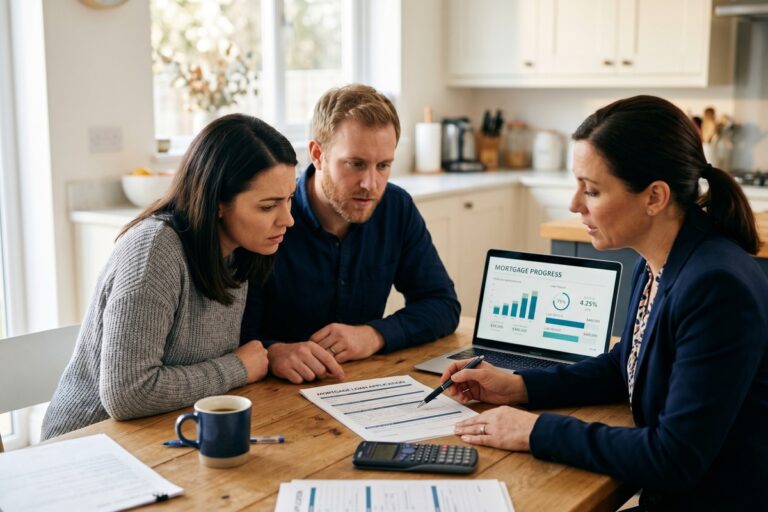
A DTI above 43% can add 0.5%–1.5% to your mortgage rate — or get you denied outright. Here's why lenders weight cash flow over credit history.
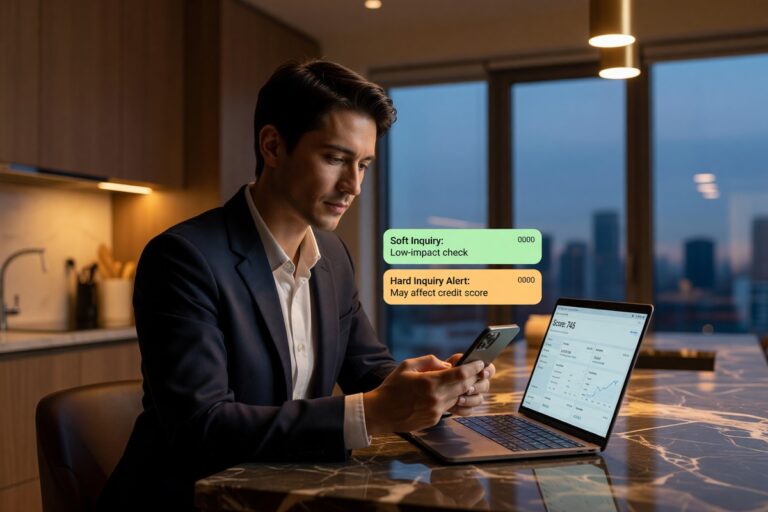
A hard pull can drop your score 5–10 points and sits on your report for 2 years—yet most borrowers trigger one without realizing it by accepting a pre-qualified offer.
A 750+ FICO score won't protect you from a 2-5 point APR jump caused by high debt-to-income ratios, multiple credit inquiries, or unverified income. Here's what lenders don't tell you.
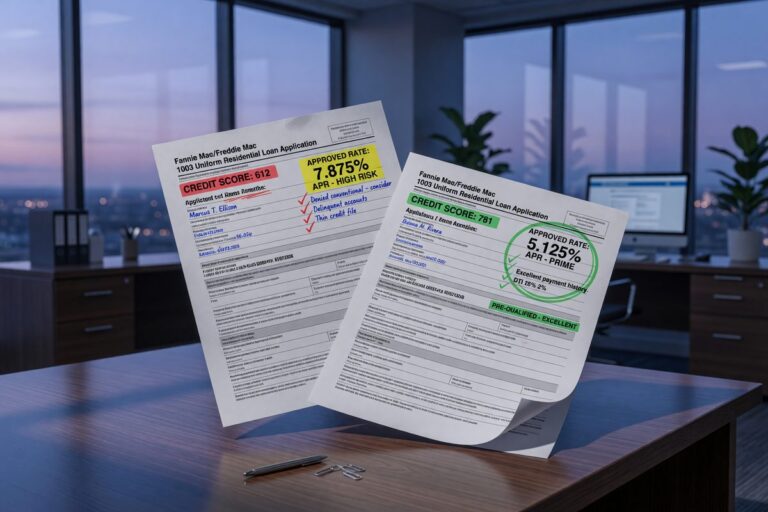
A 630 credit score co-borrower can raise your mortgage rate by 0.25–0.75%, costing $130–$200 monthly on a $400K loan. See when adding them actually makes sense.
Self and Kikoff report to all three credit bureaus and achieved 99.2% on-time payment rates in 2025. Keep utilization under 10% with automated budgeting tools to accelerate credit building.

79.6% of mortgages now go to super-prime borrowers. See whether full joint borrowing or solo applications with authorized users protect both credit profiles.

Only 23% of workers get paid family leave. Discover the proactive steps that prevent a credit score collapse when your income drops 30-100% overnight.

Paying down a maxed credit card lifts your score 10–50 points in 30 days. See why tackling debt and credit together beats choosing one or the other.
Hard inquiries drop your score by fewer than 5 points, but soft inquiry pre-qualification costs nothing. Compare offers risk-free across lenders before submitting one application.